Portage CEO argues pension funds should back more Canadian GPs and companies.
Ahead of Prime Minister Mark Carney’s Canada Investment Summit, a slew of homegrown financial institutions have pledged billions of dollars toward domestic infrastructure projects, with some making specific commitments to address a growth capital crunch. Though the financial services sector wasn’t identified as a priority by the feds in its dealbook, the industry faces similar gaps.
“There’s got to be more people at the table.”
Adam Felesky, Portage
To Adam Felesky, CEO of the Power Corporation’s FinTech investment arm Portage, the availability of capital depends on what kind of FinTech company you are: looking to capture the entire Canadian market, or chasing global customers.
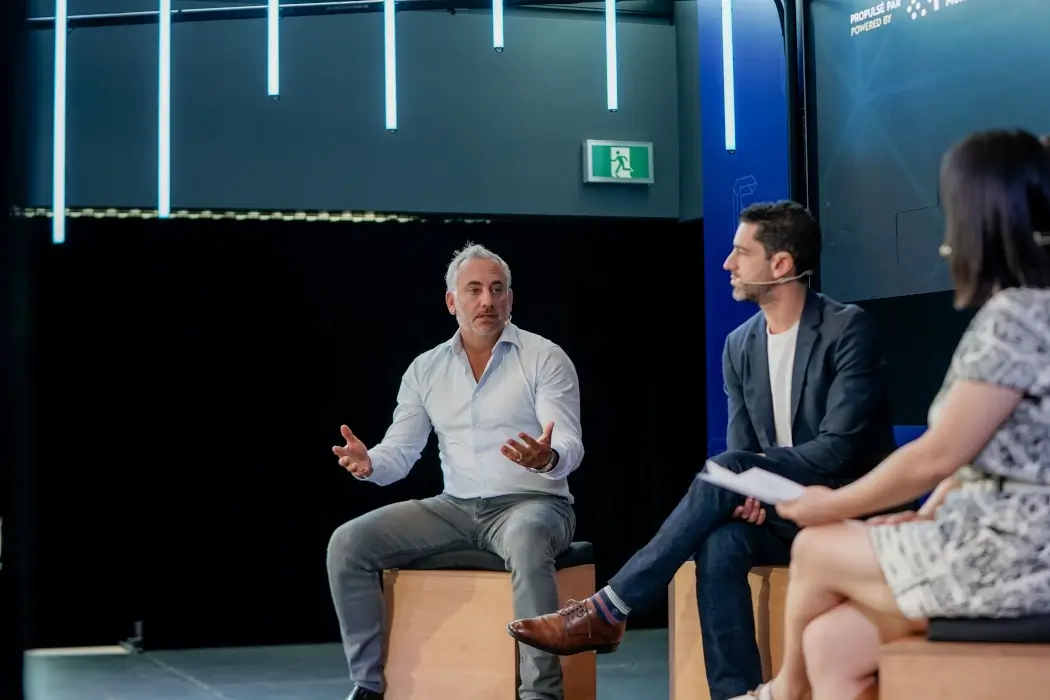
“International investors really don’t understand the [total addressable market] of this market,” Felesky said on stage at Canada FinTech Forum in Montréal on Monday, mentioning FinTechs Float and Koho as examples of startups capturing Canadian customers. “We need more capital to support our domestic companies going after this domestic market.”
BetaKit caught up with the leader of the global FinTech investor to delve more into why that capital gap exists and what could be done about it.
The following interview has been edited for length and clarity.
You said on stage that there’s little growth capital available for startups serving the Canadian market only, but lots for those selling to markets outside of Canada. Is that because a lot of the growth capital in Canada comes from financial institutions that might see startups as competition, rather than potential investments?
Maybe. I think the problem is there’s not enough Portages. It’s us, Export Development Canada, Business Development Bank of Canada, and Inovia funding growth-stage FinTech companies selling into Canada. There’s got to be more people at the table. In Canada, you kind of have to bridge between Series A and Series D, and make a very complicated bet. We funded Wealthsimple all the way to Series D. You have to bridge these companies to scale, then you need bigger funds. Because the cash we need to put into the company becomes too big of a concentration.
It’s this challenge you have, where not only do you need more funds like Portage, but you need more funds like Portage of the same size.
Where would you ideally like the domestic growth capital to come from?
I think it’s got to be the pensions backing GPs or doing direct investments.
JP Morgan is a great example: they invest billions into startups that are transforming their own businesses. So in FinTech, in particular, there’s no doubt that financial services incumbents need to be a part of it.
On stage, you said that Canada’s total addressable market is “just big enough” for domestic-facing companies. We’re seeing more competition from US entrants, like Ramp, coming in to compete with Float. Who wins, or how do Canadian companies win?
I would bet on Float all day long.
International-scale players that go into the Canadian market, they call Canada “rest-of-world.” It’s too small relative to the big markets they’re in. Wealthsimple is another example, with Robinhood coming to the Canadian market.
We just think that when vending across so many different markets, it’s much more difficult to feed a local brand that’s building very specifically for that citizen.
What are you hopeful about coming out of the Canada Investment Summit?
The tone’s changing, for sure. I think our relationships with all the different pension funds—there’s increasing interest and openness to how they can support local GPs doing direct investment. So I think that sentiment’s changing.
Feature image courtesy Canada FinTech Forum. Image by Joelle Lapointe.