Fintech success stories tend to follow a familiar pattern in the startup world. It’s often about making financial services faster, cheaper and more accessible; attracting customers that traditional banks have overlooked; and of course, scaling quickly. But there’s a rather unique issue that affects fintechs in a different way to startups in diffeent industries, and that’s safety and security aspect of dealing with money. That is, the potential problems that may arise when that growth starts to outpace the systems designed to keep customers’ money safe.
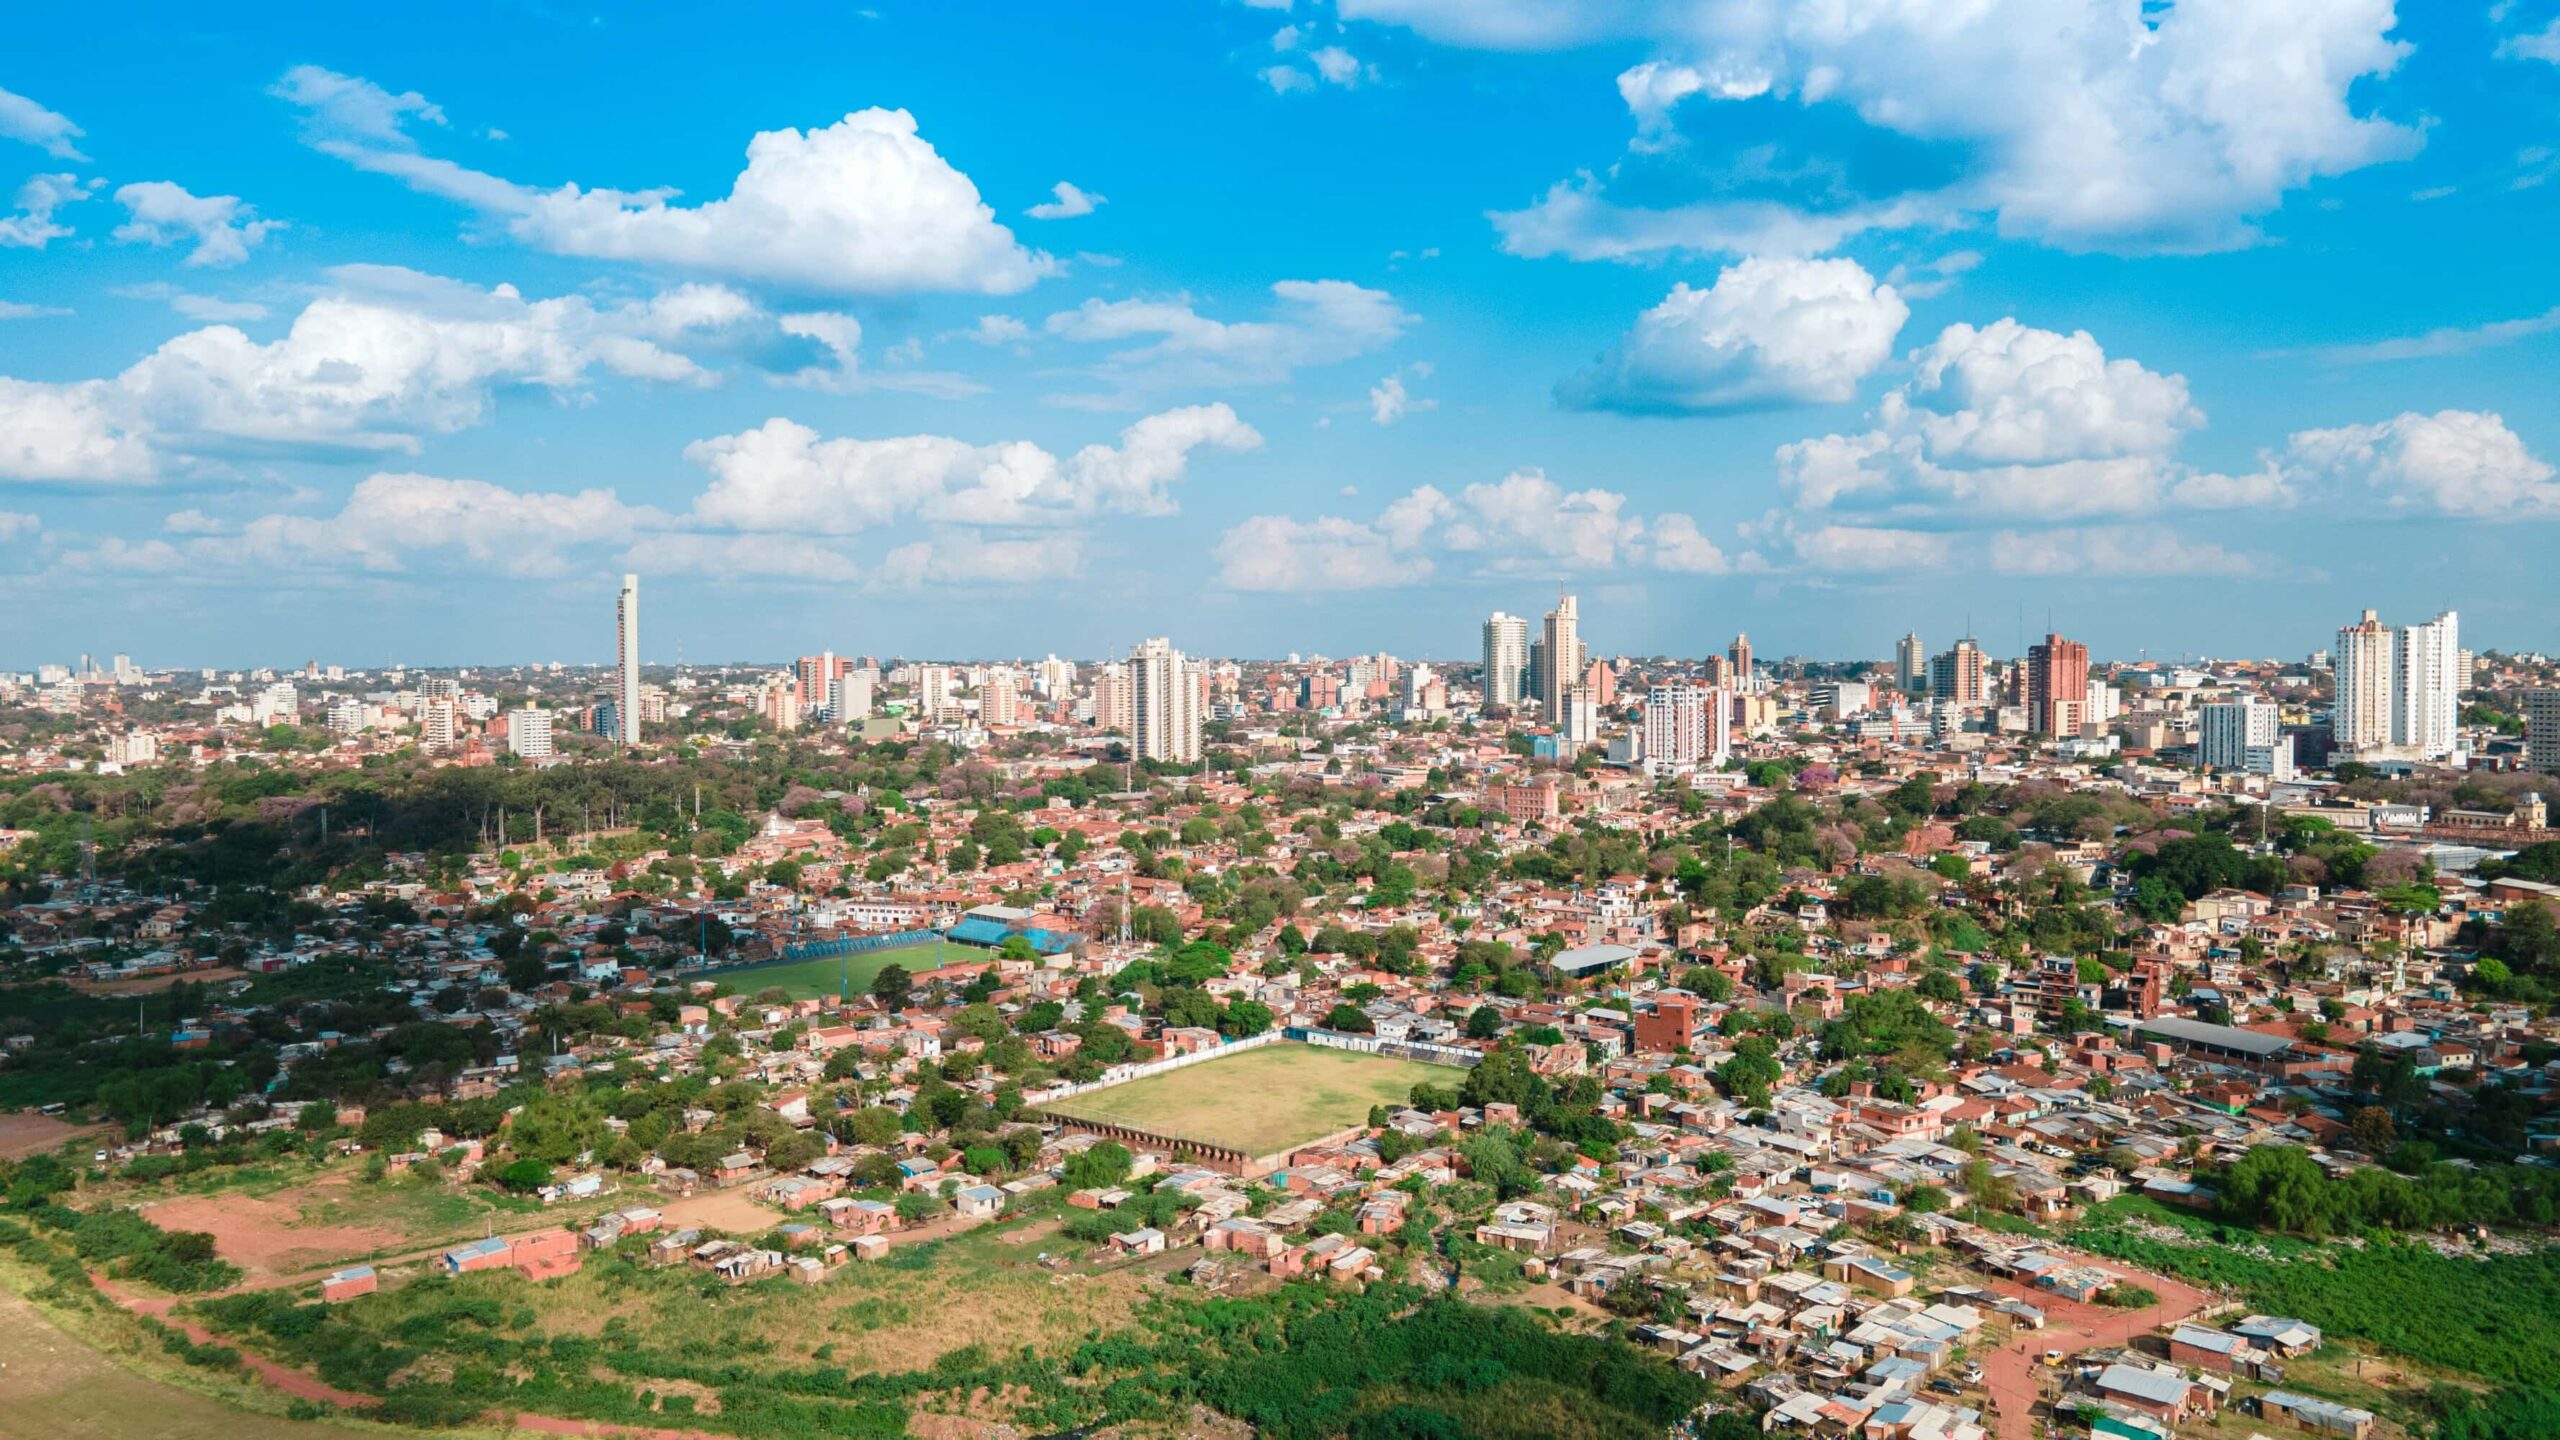
Paraguay’s Ueno Bank collapse is a pretty clear example of what can go wrong when regulation and governance don’t scale at the same rate as everything else. Launched in 2021, Ueno grew from a relatively niche fintech into one of the country’s biggest banking players in just a few years. And by June 2026, it had around three million customers in a country of approximately 6.5 million people, which is an incredible ratio by any account.
The recent issue with Ueno has since triggered a major political and financial crisis, with millions of customers affected and questions raised about the relationship between rapid expansion, corporate governance and regulatory oversight. The company may not necessatily have brought down Paraguay’s entire banking system per se, but the disruption was significant enough to expose just how much of the country’s financial activity had become connected to one institution, raising serious questinos about what should and shouldn’t be allowed in fuutre.
Once a Fintech Startup, Soon a Systemically Important Bank
Ueno’s journey began in 2021 when Grupo Vázquez acquired Financiera El Comercio and converted it into Financiera Ueno. The Ueno app launched in February 2022 which gave customers access to digital banking services, while the business itself continued expanding into other financial products.
By June 2024, Ueno had merged with Visión Banco; a move that significantly increased the company’s scale while simultaneously helping position it as Paraguay’s largest bank (in terms of customer numbers and active credit cards). In fact, its own financial reporting shows that total assets rose from around 3.1 trillion guaraníes in 2023 to almost 14 trillion in 2024, with the merger accounting for much of that jump. And at the outset, the first thing we see here is an undeniably impressive growth story. However, much like many things, the other side of the coin is that this trajectory also illustrates how quickly a technology-led financial business can become a major part of a country’s banking infrastructure, which should, at least in theory, begin to highlight some potential issues or reasons for concern (even if only hypothetical).
The problem is that becoming a bank isn’t just the next stage of a successful fintech journey. In fact, it’s the beginning of an entirely new and different path that brings a different level of responsibility to the table. A company handling payments or providing financial software isn’t necessarily carrying the same obligations as an institution taking deposits, extending credit and becoming deeply embedded in the national economy.
Indeed, what happened here is that Ueno’s collapse followed regulatory scrutiny of lending to companies that were actually linked to its controlling shareholder, Grupo Vázquez. Ultimately, Paraguay’s central bank initiated resolution proceedings after finding that the bank’s solvency ratio had fallen below half the required minimum.
Growth Is Exciting, But Governance Has To Keep Up
For fintech founders, rapid growth is often the main and ultimate goal. It means more customers, more transactions and more market share, all of which have the potential to attract investors and create opportunities to expand into new products and markets.
But the problem in this situation is that growth also creates several additional layers of complexity. A business that once had a relatively small customer base and straightforward operations can quickly find itself managing deposits, credit exposure, multiple subsidiaries, institutional investors and relationships with public-sector organisations, all of which are incredibly complicated and really do require deep understanding.
Steffan Kharmaaiarvi, Founder of Borderfolio, argues that the lesson is not that fintechs should grow slowly, but that their controls must grow alongside them. “Controls have to scale at the same rate as the customer base, not a year behind it,” he says. He adds that once a company holds customer money or data, shortcuts in governance become liabilities that grow with every new user. Insider lending and weak capital controls, he argues, are rarely sudden failures. They are often the result of processes that nobody properly owned while the business was focused on expansion.
Kharmaaiarvia’s test for founders is to ask: if the customer base doubled tomorrow, would risk, audit and reporting processes still work without the founder personally checking them? Because if the answer is no, that means that those systems need to be built before the next growth push, and there should be an immediate pause on all scaling processes taking place.
From Fintech To Traditional Bank
Transitioning from a fintech into a proper, traditional bank brings with it several layers of complexity. Private companies need room to innovate, attract investment and make commercial decisions. But once they receive a banking licence and take deposits, they’re no longer operating like an ordinary technology startup. From that point onwards, everything changes, because it means that their decisions can affect depositors, other financial institutions and, in some cases, public finances, and overall, everything they do has far wider-reaching consequences.
Of course, that doesn’t mean that a privately owned bank becomes a state-owned institution; private shareholders can still own and control it. But, the public-interest implications of its activities mean that stronger supervision, capital requirements and restrictions on lending are necessary.
The case of Ueno also raises poignant points about group structures and related-party lending, at least from a political sense. Dmitri Mihhailov, General Partner at Prifinance, says that companies under common control must be considered together when assessing exposure limits under Paraguay’s banking legislation. According to Mihhailov, rapid customer growth can disguise concentration risk, particularly where a fintech is part of a wider business group. His advice, in this case, is that founders should treat the entire group as a single risk unit before applying for a banking licence, while investors should demand visibility into related-party lending and capital above regulatory minimums.
“Not just users,” he says. “Once limits slip, Law 2334/03 kicks in automatically.” Mihhailov also expects regulators to scrutinise group ownership structures more closely when fintechs move into banking, and this is sage advice for fintechs the world over, no doubt about it.
What About the Next Generation of Fintechs?
Ueno’s collapse isn’t a blanket argument against digital banking, fintech innovation or ambitious growth. After all, its expansion brought financial services to millions of people, including customers who may have been underserved by traditional institutions.
But, what it does demonstrate is that a business can become systemically important long before its governance structures are ready for that responsibility, and that’s where the real problem lies. The risks become even more complicated when private ownership, related companies, institutional funding and public-sector money intersect.
Ultimately, the lesson that ought to be identified and learnt (hopefully) from the Ueno debacle is that regulation shouldn’t wait until a fintech has become so large that its failure threatens confidence across a national financial system. Nor should the process of obtaining a banking licence be treated as a one-off hurdle, after which the business can simply carry on scaling as before. It shouldn’t be about one opportunity to evaluate what’s going on and then stepping back and trusting from that day forth.
For founders, investors and regulators, the crossover from fintech to bank needs to be treated as a fundamental change in responsibility, not a little shift from one business venture to another. Innovation can move quickly, and we certainly know that it does, but that doesn’t mean that the safeguards around other people’s money can simply trail behind it.