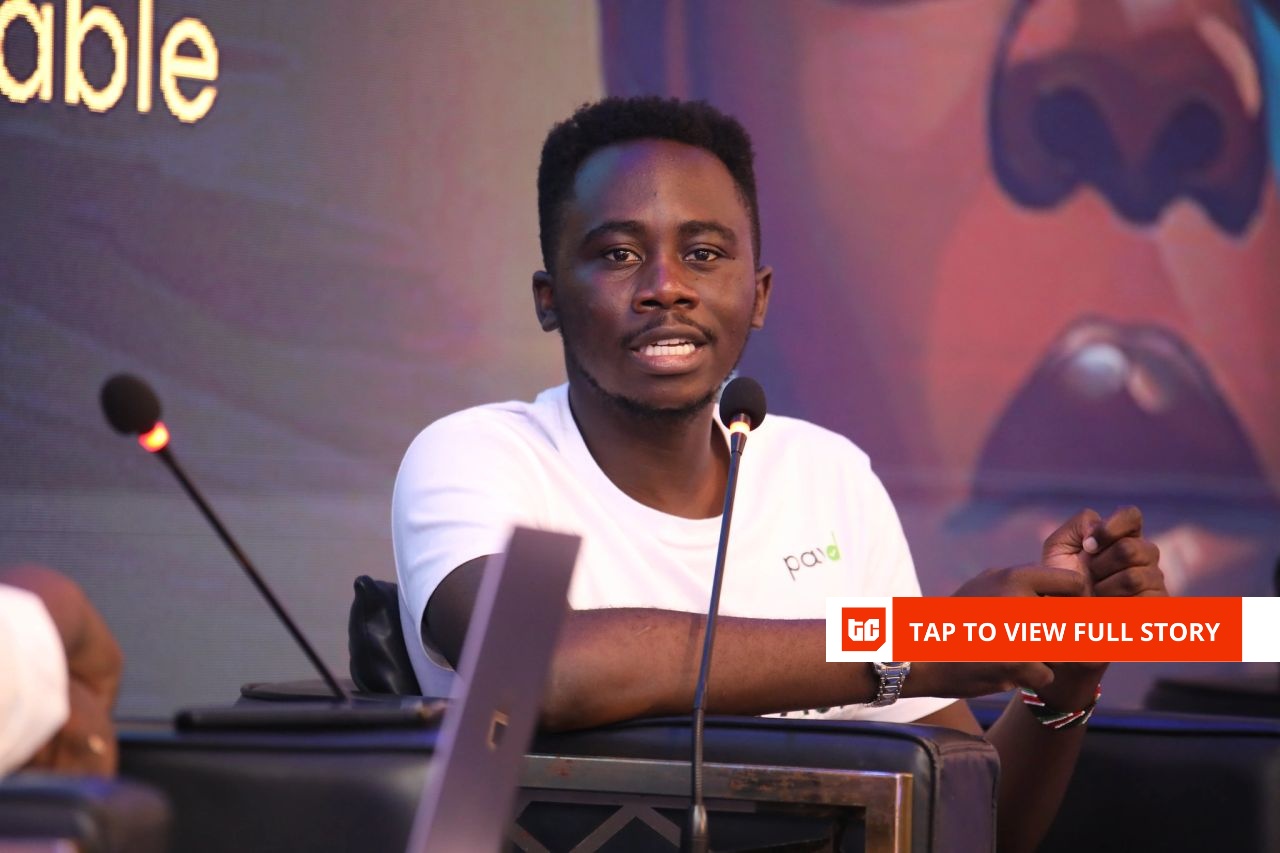
Payd, a Kenyan payments startup, plans to resume its services on Friday after foreign exchange (FX) losses left it short of the funds needed to meet some customer balances, forcing it to pause payouts around May and overhaul its treasury system.
Founded in 2023 by Benaiah Wepundi, Payd enables freelancers, contractors, and businesses to receive international payments and convert them into local currencies. As of February, Payd said it served about 30,000 users across Kenya, Nigeria, South Africa, and Senegal.
Payd’s experience highlights one of the less visible risks in Africa’s cross-border payments market: a fintech can generate millions of dollars in payouts while still losing money if it fails to properly match the currencies, timing, and cost of the funds moving through its system.
Payd has denied shutting down after its services stopped working, leaving customers unable to complete some transfers and questioning the company’s silence over the disruption. Posts from customers on X also raised concerns about failed or delayed transfers, with some saying the service stopped working without a clear explanation.
The company plans to restart services across its app, WhatsApp chatbot, business platform, and application programming interface (API) on Friday, September 18, Wepundi told TechCabal in an interview on Wednesday.
“Ahead of the restart, users will be able to track their existing balances and choose the accounts into which settlements will be paid,” Wepundi said.
But the restart follows months in which Payd’s rapid growth exposed weaknesses in its treasury controls. The company’s monthly payment volume rose from about $500,000 in September 2025 to more than $3 million in April and May 2026, according to Wepundi. During that period, Payd expanded to 52 currencies at its peak, then cut to 35 and now plans to reduce it further to 13. It relied heavily on US dollars for incoming payments and local currencies for customer payouts.
The company did not adequately account for the cost of maintaining those local currency obligations as exchange rates moved, Wepundi said. By the time Payd understood the full extent of the problem, the accumulated FX losses had affected the funds available to cover some customer balances.
“At times, the dollar cost of making those payouts was higher than the dollar amount received to fund them,” Wepundi said. “We didn’t accurately track these changes across the rates we offered on the platform and the rates our providers offered.”
“The treasury model we used did not fully account for changes in USD to local currency between pre-funding and payout and the conversion prices charged by our payment partners. Funds for payments were managed in a shared pool across US dollar and local-currency accounts. Most incoming payments were in dollars, while many payouts were in local currencies.”
A $100 payment could be prefunded at an exchange rate of $1 to 10 units of local currency, only for the customer to withdraw five days later when the rate had moved to 1$ to 13 units of the same local currency. Payd would then need to provide more local currency than it had originally set aside. Across multiple currencies, payout dates, and provider-specific rates, the company lacked a sufficiently precise system for tracking those exposures, Wepundi said.
“Our monitoring did not identify the full effect of the losses early enough. We take responsibility for that.” Wepundi said.
From growth to a payout crunch
Payd’s payout problems became visible to customers in May, when Payd paused some payouts. Two customers told TechCabal at the time that they couldn’t use Payd to make transfers to Nigeria. When one contacted the company, Payd attributed the disruption to “downtime on the app.”
Payd’s case puts it in a wider context for African fintechs whose business models depend on moving money between currencies and payment networks. Cross-border payments can look attractive because revenue grows with transaction volume. However, the economics also expose companies to liquidity, settlement, and FX risks between the moment money enters a system and the moment it leaves.
The Noah partnership in February enabled Payd to embed stablecoin-based payment rails. By March 2026, the company was marketing access to over 35 countries and described itself as a platform for “borderless” workers and businesses. According to its website, the company relies on licenced payment providers and virtual asset service providers (VASPs) for regulated financial services, rather than providing those services directly.
Payd had also reported strong growth. In January, Wepundi told Disrupt Africa that it reached break-even in September 2025 with average monthly recurring revenue (MRR) of about $10,000. In December, Wepundi said Payd had crossed $1 million in monthly transaction volume and targeted $10 million in monthly transaction volume and $300,000 in MRR over the next 12 months.
He said the business generated revenue from transaction fees, FX margins, and business-to-consumer (B2C) products such as APIs and bulk payments.
The subsequent rise in payment volume, however, increased the amount of money flowing through the system and, consequently, the error in its treasury model.
The economics of the mismatch
Payd charges fees on incoming payments and payouts and earns a margin when customers convert currencies.
Wepundi said the company earned about $1.5 from $100 processed on average, while payment providers took between 30 cents and 75 cents, leaving Payd with roughly 75 cents to $1.2 before operating costs such as staff, tech, and compliance.
He said the fee structure itself wasn’t the source of the losses; the bigger problem was how Payd managed the relationship between dollar-denominated customer balances and the local currencies needed to pay those customers.
“To make the model sustainable, we needed fewer supported currencies, access to local funds when a payout was due, and closer checks on exchange rates and the actual cost of each payment,” Wepundi said.
Payd is now reducing the number of currencies it supports and changing how it sets money aside to meet customer settlement obligations. The company plans to maintain a separate record of each customer’s balance and reconcile it against the funds held to meet it.
The company is also working with local partners to source currency when a payout is due rather than holding large amounts of local currency in advance (prefunding) and repeatedly converting funds across several markets, reducing its FX risk exposure.
Wepundi said Payd reduced its team from eight people earlier this year to six, with four full-time co-founders and two part-time engineers, as the company cut costs.
Funding pressure
Payd’s treasury struggles were compounded by limited access to fresh capital and difficulty raising follow-on funding. According to Wepundi, the company has explored strategic partnerships, funding, and potential mergers or acquisitions over the past six months.
Wepundi had told TechCabal in 2025 that it was raising a pre-seed round. Payd secured about $110,000 toward the round across 2025 and 2026, but did not complete the raise as fundraising slowed around March and April, he said. The company had intended to use some of that capital for regulatory and licencing work in the United States, Canada, and Rwanda. Those plans were subsequently paused.
According to Wepundi, Payd has raised $123,000 from investors, including $48,000 from Nairobi Business Angels Network (NaiBAN) in 2025 and $50,000 from Kaleo Ventures in Q1 2026.
The company has also received $43,000 in grants and other support from blockchain networks Celo—through Prezenti and Mozilla Africa—and Lisk, bringing its total funding and non-equity support to $166,000.
The company now plans to fund its day-to-day operations from revenue and put what remains towards the customer deficit over the next six months, rather than raise a large round immediately.
Wepundi did not disclose the size of the deficit.
A restart, and a test of trust
At least three people familiar with the situation told TechCabal that Payd has explored a potential sale, which Wepundi confirmed.
“Over the past six months, we have explored strategic partnerships, strategic funding, and potential mergers or acquisitions. Those discussions are ongoing,” Wepundi said. “We are assessing these options against the same priorities: settling customer balances, keeping Payd operating, rebuilding value for existing and future investors, and building Payd as the go-to infrastructure for payments for the future of work.”
The immediate priority, however, is to get the payments platform operating again under a different treasury model, Wepundi said. Payd’s challenge now is to prove it can safely manage the money moving through its system.
Payd’s restart will be harder than bringing its payment rails back online. It must clear the customer shortfall while proving that its new treasury model can keep pace with the money flowing through the business.
The company grew its monthly payment volume sixfold in less than a year. Its next phase will depend on whether it can manage that money without repeating the currency mismatches that put customer balances at risk.
“We have worked with regulated partners for services requiring authorisation, and our immediate plan is to continue with that approach while restoring financial and operational stability,” Wepundi said. “We would then resume raising capital for our own regulatory approvals and further expansion.”
True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.