Getting startup stock options can feel like receiving a ticket to a future payday. The reality is more complicated. Before exercising, employees need to understand not only what their options could be worth, but also what exercising them could mean for their taxes. A free stock-option exercise and AMT calculator can help employees get an initial estimate of the potential tax impact before making that decision.
The part that catches many people off guard is that a tax bill can arise before there is any sale and, in some cases, before the employee has received any cash from the shares.
For startup employees holding Incentive Stock Options (ISOs), the Alternative Minimum Tax, or AMT, is particularly important to understand.
The Tax Question That Often Gets Missed
A stock option gives an employee the right to purchase shares at a predetermined price, known as the exercise price or strike price.
If the company’s value has increased since the options were granted, the shares may be worth more than the price the employee has to pay to acquire them. The difference between the current value and the exercise price is commonly called the spread or bargain element.
That difference can become important for tax purposes.
With ISOs, exercising the options can create an AMT adjustment based on the bargain element in the year of exercise. The employee doesn’t necessarily have to sell the shares for this issue to arise.
That creates an unusual situation.
An employee can spend money to exercise an option, continue holding the shares, and still have to think about a potential tax liability associated with the exercise.
For someone who has never dealt with startup equity before, that can be an expensive surprise.
ISOs and NSOs Are Not Taxed the Same Way
One of the first things an employee should establish is what type of stock option they actually have.
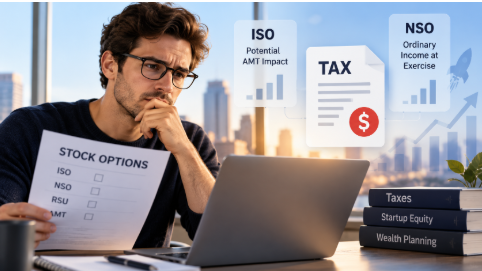
The two common categories are Incentive Stock Options and Nonqualified Stock Options. Their tax treatment is different, which means the consequences of exercising them can also be different.
Incentive Stock Options
ISOs receive special treatment under US tax rules, but they come with their own complications.
When an ISO is exercised, the bargain element can be relevant when calculating alternative minimum taxable income. Depending on the employee’s overall tax situation, that calculation can result in an AMT liability.
The important detail is timing.
The potential AMT issue can arise in the year the options are exercised, rather than waiting until the employee eventually sells the shares.
This is one reason an employee shouldn’t look only at the exercise price when deciding whether exercising is affordable.
Nonqualified Stock Options
NSOs work differently.
When an NSO is exercised, the spread between the fair market value of the shares and the exercise price is generally treated as ordinary income.
In other words, the tax event generally occurs at exercise rather than requiring the employee to wait until the shares are sold.
The exact tax outcome depends on the individual’s circumstances, but the basic distinction is important: ISOs can create an AMT issue, while NSOs generally create ordinary income at exercise.
Knowing which type of option you have should therefore be one of the first steps in evaluating an exercise decision.
What Makes the AMT So Confusing?
The Alternative Minimum Tax is essentially a parallel federal tax system.
A taxpayer’s liability is calculated under the regular tax rules and under the AMT rules. The applicable rules determine whether the taxpayer owes more under the alternative system.
That’s where startup stock options can make things complicated.
An employee might look at their regular tax situation and see no obvious reason to expect a large additional tax bill. But an ISO exercise can affect the AMT calculation because of the bargain element.
The result isn’t necessarily that every ISO exercise creates an AMT liability. It depends on the employee’s broader financial and tax circumstances.
But the possibility is important enough that it should be considered before exercising.
The Exercise Price Isn’t the Whole Cost
This is probably the simplest way to think about the problem.
When employees receive options, they often focus on the strike price. If they have the right to buy shares at a relatively low price, exercising can appear straightforward.
But the actual cash requirement may be larger than the exercise cost itself.
The practical equation is closer to:
Cost of exercising + potential tax = potential cash requirement
For an ISO holder, the potential AMT impact is part of that second piece.
This doesn’t mean an employee will automatically owe AMT after exercising ISOs. The actual result depends on the individual’s income, deductions, other AMT adjustments and other circumstances.
It does mean that calculating only the amount needed to purchase the shares may give an incomplete picture.
Why Startup Employees Should Think About Timing
Private-company stock doesn’t work like a publicly traded stock.
If someone exercises options in a public company, there may be an established market for the shares. Startup employees often don’t have that luxury. Their shares may remain private and difficult to sell.
That makes the timing of an exercise decision particularly important.
Suppose the value of a startup increases significantly after an employee receives an option grant. The difference between the exercise price and the current value may become much larger.
A larger spread can mean a larger potential tax consideration for an ISO exercise.
On the other hand, exercising requires cash, and there is no guarantee that the shares will eventually become liquid or increase in value.
That’s the tension employees need to understand.
The decision isn’t simply about whether the company’s valuation might increase. It’s also about how much cash the employee is comfortable committing, the potential tax consequences and the possibility of holding an illiquid asset for an extended period.
A Few Numbers Can Change the Picture
Before exercising, employees should gather the basic information attached to their equity grant.
That usually includes the number of options, exercise price and relevant information about the current value of the shares.
From there, an employee can begin estimating what the exercise might look like financially.
This doesn’t predict what the shares will ultimately be worth. It simply helps answer a more immediate question: what could exercising cost me today?
That distinction matters.
Startup equity is often discussed in terms of its potential future value. The more practical question before exercise is what the employee has to spend now and what tax consequences could come with that decision.
What Employees Should Check Before Exercising
There isn’t one exercise strategy that makes sense for everyone. Individual circumstances can be very different.
Before making a decision, an employee may want to check:
- Whether the options are ISOs or NSOs
- The exercise price for the options
- The current relevant value of the shares
- The difference between that value and the exercise price
- Whether an ISO exercise could affect their AMT calculation
- The potential ordinary income from exercising NSOs
- How much cash would be needed to exercise
- Whether the resulting shares are currently liquid or restricted
- Whether the company has restrictions on transferring or selling the shares
- What tax and holding-period rules may apply to their situation
The goal isn’t to predict every future outcome. It’s to avoid making an exercise decision without understanding the major pieces of the equation.
Don’t Confuse Paper Value With Cash
This is another important distinction for startup employees.
An option can have significant potential value on paper without putting money in the employee’s bank account.
Until there is a way to sell the shares, that value may remain illiquid. Meanwhile, the employee may have already spent money exercising the options and could have tax obligations to consider.
That’s why startup equity requires a different way of thinking about value.
A large difference between the strike price and current share value may look attractive, but the employee still needs to consider the cost of acquiring the shares and the tax implications that may follow.
Where a Calculator Fits In
Employees don’t necessarily need to build a complicated spreadsheet before they can start thinking through the numbers.
A calculator can provide a useful first look at the relationship between the exercise price, current value and potential AMT implications.
PrivateTechShares, which builds plain-English tools for people navigating startup equity and liquidity, offers a calculator designed specifically around the stock-option exercise and AMT question.
It can help employees get an initial estimate in a few seconds without signing up. From there, they can take the numbers to a qualified tax professional and discuss how their individual circumstances may change the result.
That’s an important distinction: a calculator can help someone understand the potential issue, but it isn’t a substitute for professional tax advice.
The Bottom Line
Exercising startup stock options isn’t simply a matter of paying the strike price and waiting for the shares to become more valuable.
For ISO holders, the bargain element can affect the AMT calculation in the year of exercise, even when the shares haven’t been sold. For NSO holders, the spread is generally treated as ordinary income when the options are exercised.
The tax treatment can therefore turn what looks like a straightforward equity decision into a more complicated financial calculation.
Before exercising, employees should understand what type of options they hold, how much the exercise will cost, what tax consequences could arise and whether they can comfortably handle the cash requirement while the shares remain illiquid.
The earlier those questions are considered, the less likely the tax bill is to become an unpleasant surprise.