Valley National Bancorp has spent 99 years building a regional bank. Rather than spend years more building a digital deposit base from scratch, it’s buying a Jersey City fintech outright.
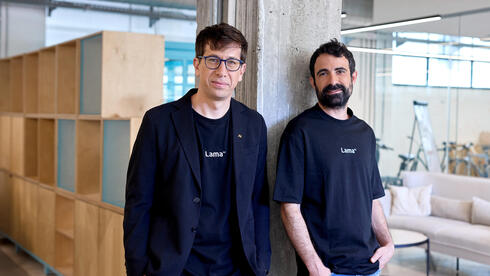
Valley National Bancorp said it will acquire Bluevine for roughly $340 million, paying about 75% in cash and 25% in Valley stock. The small-business banking fintech, founded in 2013 by Israeli entrepreneurs Eyal Lifshitz and Nir Klar and now headquartered in Jersey City, serves around 175,000 active small-business customers through a digital platform that bundles checking, lending, invoicing and bill pay. The deal is expected to close in early 2027, pending regulatory approval.
That customer base isn’t the main attraction. What Valley actually wants is the money sitting inside it.
Bluevine brings with it about $2.1 billion in low-cost, digitally sourced deposits, the kind that didn’t require Valley to open a single new branch to collect. Those deposits grew at roughly a 35% compound annual rate from 2023 through the second quarter of 2026, a pace no 230-branch regional bank built on brick-and-mortar New Jersey and New York retail banking is going to match organically. Valley, chartered in 1927 and sitting on more than $66 billion in total assets, is effectively paying for growth it couldn’t generate on its own fast enough.
There’s a second asset in the deal that matters just as much: engineers. The acquisition adds roughly 180 R&D and engineering staff spread across Redwood City, Jersey City, Salt Lake City and Tel Aviv. Valley has been trying to build out an AI and technology strategy, and buying a functioning fintech’s product and engineering org is a faster path to that than hiring one developer at a time.
For years the storyline in banking was fintech versus incumbent: Chime, Bluevine, Brex and others pulling small-business and consumer deposits away from traditional banks with slicker apps and fewer fees. Valley’s move flips that script. Instead of competing with Bluevine for the same small-business customer, it’s just buying the customer relationship, the deposits and the team that built it.
It also lands at a moment when neobank valuations are under real pressure. Funding for standalone fintechs has gotten harder to raise at the multiples these companies commanded a few years ago, and an acquisition by a federally chartered bank gives Bluevine’s backers an exit at a fixed price rather than another funding round dependent on market sentiment. Bluevine had raised venture funding across multiple rounds since its 2013 founding; this deal converts that into a cash-and-stock outcome instead.
Frankly, this is the more interesting M&A story in regional banking right now, more interesting than another branch consolidation or cost-cutting merger. Those deals shrink a bank. This one is Valley paying real money to get bigger in exactly the places, digital deposits and engineering talent, where its existing footprint doesn’t help it at all.
Bluevine’s own history explains why it was a sensible target. The company started as an invoice-factoring business in Tel Aviv before Lifshitz and Klar relocated its U.S. headquarters to Silicon Valley, and then moved that U.S. base again to Jersey City in January 2023. It pivoted over the following decade into full small-business banking, adding checking accounts and lending products on top of the original factoring product. That evolution from a single lending niche into a broader deposit-gathering platform is exactly what made its deposit base worth $2.1 billion to an acquirer, rather than a few hundred million.
What happens between now and closing is the part worth watching. Regulatory approval for bank acquisitions of this size isn’t automatic, and the 15 months between signing and an early-2027 close give both sides time for the deal to slip or for terms to shift. Valley hasn’t said whether Bluevine will keep operating under its own brand or get absorbed into Valley’s retail products, and that answer will tell small-business customers more about what’s actually changing than the deal’s price tag does.
Also read: BitMine now owns nearly 5% of all the ether that will ever exist • Copper quietly hits record highs while gold barely moves in 2026 • JPMorgan says lenders now demand proof AI firms can repay debt
This article is posted in Financial Markets News, check it out for more related stories.
Almost there. Sign in and your reply posts straight away.