The startup, which Blackbird said is its fastest growing investment ever, has hit $50 million in annualised revenue and is now moving to agentic healthcare.
Key Takeaways
- Heidi has hit unicorn status, securing capital at a $1.26 billion (US$900 million) valuation.
- The startup raised US$100 million via a traditional equity sale, with an extra US$240 million in customer-acquisition finance from Silicon Valley giant General Catalyst.
- Heidi began its life as an AI scribe to automate note-taking for clinicians, but is expanding into agentic care.
- The cash from General Catalyst is similar to a debt facility – it can be used for sales and marketing, with resulting revenue to be paid back to the VC with interest on top.
- Heidi is betting it can use the facility to attract new customers who will stick onto its platform long after it pays General Catalyst back.
- Blackbird led the capital raise, with participation from existing backers Phoenix Court, Point72 Private Investments and Headline.
- Heidi’s annualised revenue hit $50 million in April, up from $1 million two years ago.
AI healthcare startup Heidi has become Australia’s fourth unicorn of 2026, raising capital at a $1.26 billion valuation as it looks to hit break-even territory on its breakneck growth by the end of next year.
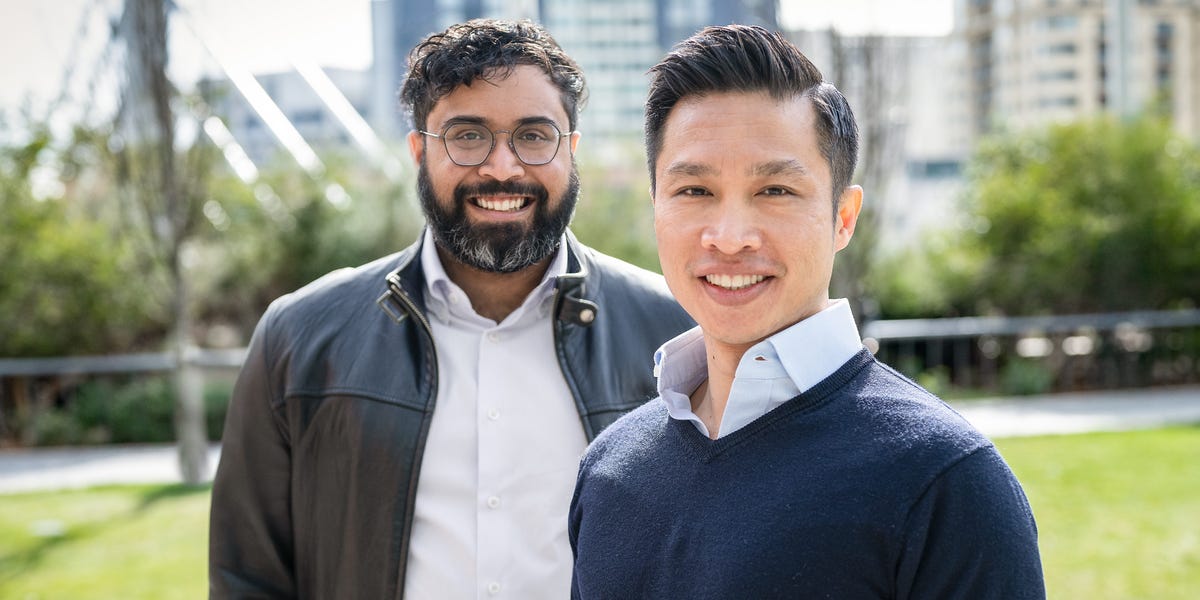
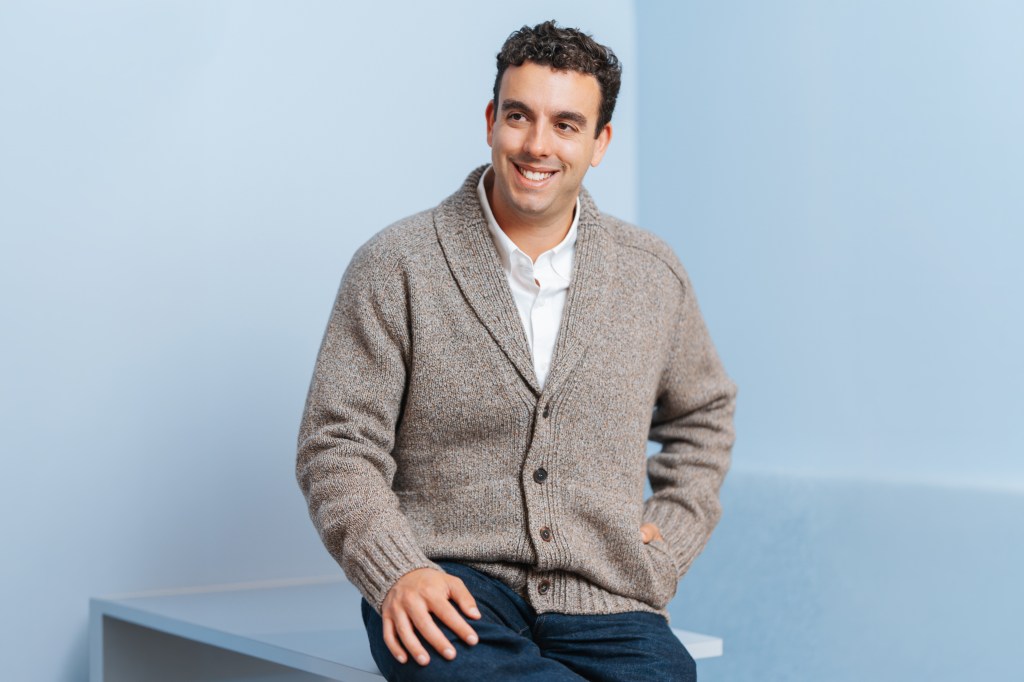
The startup is growing at a dizzying speed, with annual recurring revenue booming 50-times over in two years to $50 million. Though co-founder and CEO Tom Kelly declined to disclose Heidi’s losses, he said its cash-burning days would not last too much longer.
“The lion’s share of the funding and where we’re spending money is in new markets, like France and Germany,” Kelly said in an interview. “By the end of next year we should be cash-flow neutral… there’s a clear line of sight to be in a position where we can basically break even on any given month.”
Blackbird, which backed Heidi during its 2021 seed round and led this US$100 million Series C, has called Heidi its fastest growing portfolio ever. While Kelly said Heidi would likely remain unprofitable on a GAAP basis – meaning it would continue to spend heavily on share-based employee compensation – it would be a meaningful achievement for the startup to continue growing at its pace while breaking even.
“We’ve backed Tom and the team since their pre-seed in 2021 and our conviction is greater than ever,” Blackbird partner Michael Tolo said. The VC in August said it owned 35 per cent of Heidi, though its leading investment in the startup’s Series C was not accounted for.
Heidi’s balance sheet is about to get a little more complex, however, thanks to the US$240 million in growth financing it has received from General Catalyst. The customer-acquisition finance can only be used on marketing and sales. Revenue generated by customers acquired via these functions will funnel back to General Catalyst, with interest on top.
It was attractive to Heidi, Kelly said, because it meant hundreds of millions in funds without having to sell equity. Heidi’s bet is that it can use the funds to attract clinicians, practices and hospital networks to its platform, who will stick as paying customers for years after the VC has been paid back.
“It’s a slightly more flexible facility because we have this commitment for US$240 million that can last us roughly four and a half years,” Kelly said. “It means we’re less on the hook to go do equity raises every 12 to 18 months to keep growing business.”
Heidi is known for its free AI scribe tool that automatically takes notes for clinicians as they treat patients, cutting the enormous amounts of time healthcare professionals spend on paperwork and thus allowing them to focus on actually treating patients.
It has in recent years added paid features like session linking that creates a profile out of a patient’s history, the integration of clinical research into scribe, and communications tools between clinicians and patients. The next step is more direct care via AI agents, with Heidi saying announcements on that will be coming soon.
Kelly said about half of Heidi’s users stick to free tools only, with half having upgraded to get the premium features. The startup is benefitting from compliance systems at large healthcare providers like hospitals, Kelly said, where formalised agreements are are common and ad-hoc adoption among individual clinicians is frowned upon.
“Most healthcare is employed in larger health systems, so as we sell more into organisations… there’s this sort of natural shift towards more paid,” he said.
Heidi follows energy tech startup Neara, rocket launcher Gilmour Space Technologies and dual use Advanced Navigation in becoming a unicorn this year.
Want to see more Forbes articles on your feed? Tap here to make Forbes Australia a preferred source on Google.
Look back on the week that was with hand-picked articles from Australia and around the world. Sign up to the Forbes Australia newsletter here or become a member here.