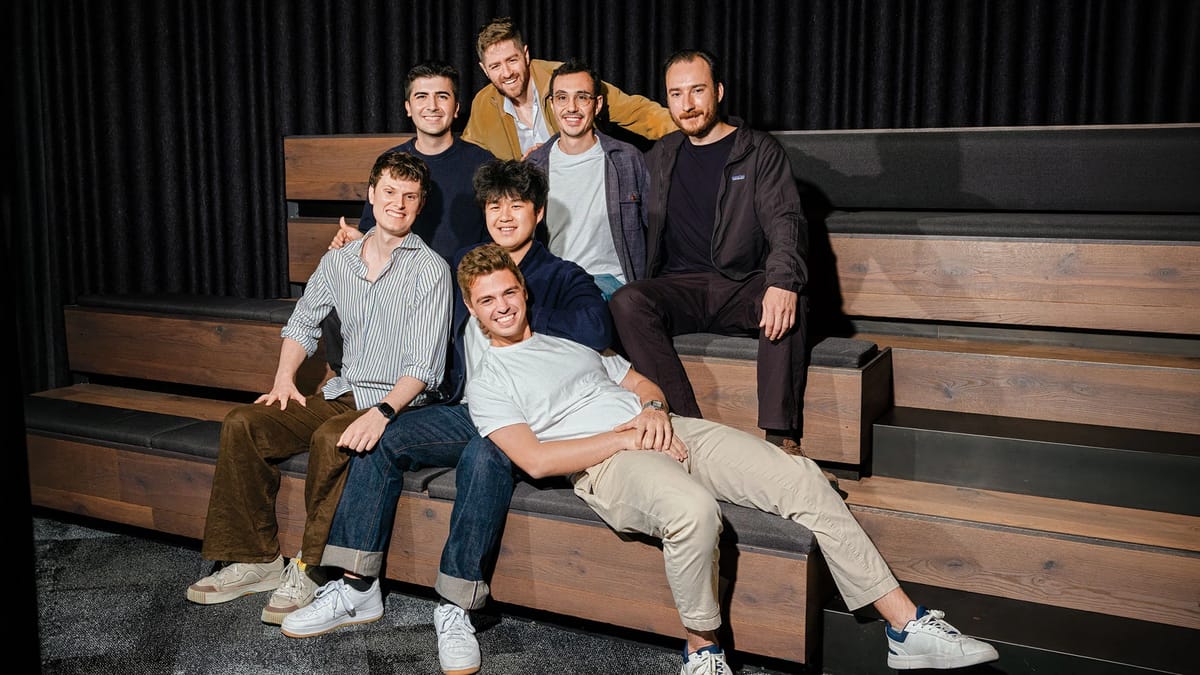
(Top) Ramp co-CEO Eric Glyman; (middle row) Crosby’s John Sarihan, Ramp co-CEO Karim Atiyeh, and Moab’s Patrick Anderson; (front row) Cleo Health’s Ben Rosand, Scope Health’s Yunyu Lin, and Silna’s Pavel Asparouhov. Photo: Lanna Apisukh
Hello, welcome back to Inc.’s 1 Smart Business Story! Today we’re looking at a company with an unusual hiring pitch: come work here, learn how to build things, and then leave to start your own company.
That’s the approach at Ramp, the New York City fintech run by co-CEOs Eric Glyman and Karim Atiyeh. According to the private-company data firm Specter, 97 former employees have left to start their own companies so far. Together those startups have raised about $400 million in publicly disclosed funding, and more than 30 are still in stealth.
That hasn’t stopped Ramp from growing too, Inc. staff writer Brian Contreras writes. In October it announced a $1.85 billion funding round at a $60 billion valuation. Instead of viewing their employee’s exits as brain drain, Glyman sees it as an advantage. In fact, one alum called Ramp “Y Combinator lite.”
In this story you’ll discover:
-
Why Ramp treats employees leaving as part of its business model
-
How maintaining strong relationships with former employees contributes to Ramp’s growth
-
That developing their employees relies on trusting their decision making and a decentralized company structure
The New York City-based fintech is the newest, hottest founder factory—and losing great employees may be the secret to its success.
From a window in his software company’s sun-dappled Manhattan offices, looking out across 22nd Street in New York City’s bustling Flatiron district, Patrick Anderson can still make out the home base of his former employer, the financial technology powerhouse Ramp. “Look outside,” he says. “You see the red brick with the arches? That’s Ramp.” His old company looms large over his current one, a construction tech startup called Moab, in more ways than one: Ramp, he explains between sips of pu-erh tea, “gave me the confidence to do this.”
Anderson isn’t the only former Ramp employee who has left to start a business just blocks away. Down the street from Moab are the health care startup Sonata and the VC firm Pathlight, both founded by ex-Rampers. Walk a few blocks north and you’ll hit the generative AI startup Melius, the insurance automation company Silna, the consumer credit card business Made Card, and the medical coding and documentation startup Cleo Health. All four were also founded by—you guessed it—Ramp alumni.
At latest count, the number of Ramp employees who have left and launched their own startups stands at 97, according to private company data firm Specter. Together, their companies have raised around $400 million in publicly disclosed funding; more than 30 are still in stealth.
One might look at the exodus of talent from Ramp and worry about brain drain: If all these former Rampers are skilled enough to build new companies from scratch, isn’t their departure cause for concern? But for Ramp co-founder and co-CEO Eric Glyman, creating a springboard for new entrepreneurs is a feature, not a bug.
“We explicitly look for people who want to be founders,” Glyman says. Indeed, building a reputation as a founder factory has helped Ramp lure ambitious young talent through its doors and, once those employees have cut their teeth and moved on, turn their subsequent startups into clients, vendors, and even acquisition targets.
The result is a tight-knit community of ex-Rampers who continue to support one another long after their work together is done. They’ve even adopted a nickname for themselves that nods to other influential tech alumni networks: the Ramp Mafia.
One reason Glyman is so obliging when it comes to his employees leaving to start their own ventures is that he did the same thing himself—twice. After graduating from Harvard in 2012 with a degree in economics, Glyman landed his first job as an analyst at the financial advisory Millstein & Co. Just two years later, he decided to launch his own business.
“When I said I was thinking about leaving, they said, ‘How can we support you?’” he says. He even recalls Jim Millstein, the firm’s founder, telling him: “I started this place. I’d be a hypocrite if I didn’t say I supported entrepreneurship.”
With Millstein’s blessing, Glyman left in 2014 and launched a startup called Paribus alongside Harvard classmate Karim Atiyeh. The company helped online shoppers secure partial refunds when products they’d purchased dropped in price. In 2016, Capital One acquired it for an undisclosed sum. Glyman and Atiyeh stayed on at the financial service behemoth, as did software engineer Gene Lee.
While there, the trio developed an interest in corporate cards, which they thought were bloated and unduly focused on rewarding spending rather than helping companies spend less. At the same time, they wanted to empower employees with more latitude.
Looking to offer an alternative model, Glyman, Atiyeh, and Lee left Capital One and, in the summer of 2019, soft-launched Ramp. Its core offering was a corporate card that came with spend-management software to track expenses and identify waste. Ramp has since expanded beyond charge cards to other B2B finance services, such as accounts payable and business banking, while also pulling together an impressive roster of clients, including Glossier, Stripe, Shopify, Uber, and Visa.
Ramp hit unicorn status in 2021, and in October announced a $1.85-billion funding round at a $60-billion valuation. Investors include General Catalyst, Sequoia, and Thrive Capital. Today, more than 3 percent of all U.S. corporate card transactions happen over Ramp’s wires, according to the company.
That Ramp has achieved all this despite some of its best and brightest leaving to launch their own ventures is not, in Glyman’s eyes, as contradictory as it might seem. “There’s an incredible return to finding people who have strong drive, strong intelligence,” the CEO explains. “It comes with some heartburn, but I think the highs are worth it.”
In fact, the Ramp-to-founder pipeline is something the company actively cultivates, beginning with its hiring strategies. Ramp will pitch itself to candidates as a place they can hone their entrepreneurial skills before eventually leaving to start a business. “A lot of companies don’t want to hire those folks,” explains Glyman, whose recruits range from tech-savvy youngsters to former founders looking to get their hands dirty again. “We say, ‘Look, if you decide to go and start a company one day, we want to help.’”
5 More Smart Business Stories:
Advertisement:
Stop funding the middleman. Start funding performance.
Every dollar you pay a middleman is a dollar not driving results.
With Universal Ads, 100% of your budget goes on screen, across premium publishers like NBCUniversal, FOX, and Paramount. New advertisers: use code UALAUNCH26 at sign-up for $2,500 in matched credits when you spend $2,500.